
AI Costs Rise With Usage: How Can Enterprises Improve Model Efficiency?
Traditional automated systems were generally limited to executing predefined, fixed workflows. For example, an e-commerce platform could automatically reorder inventory when stock ran low, and a cloud service could automatically charge based on usage. However, humans still had to configure the trading rules, suppliers, and payment methods in advance. AI agents are different because they can interpret relatively ambiguous objectives, proactively search for services, compare pricing and quality, and complete multistep operations within a defined authorization scope.
Recently, AI products have expanded beyond chat and content generation into programming, customer service, office productivity, data analysis, and automated procurement. This expansion has brought machine-native transactions into focus. In the future, an AI Agent could determine how much hashrate a user needs, request quotes from multiple suppliers, purchase API call capacity, pay with stablecoins, and deliver the result to another Agent. The entire process may not require a human to approve every individual transaction.
This raises a fundamental question: If AI agents are to participate meaningfully in economic activity, what accounts will they use, how will they make payments, and who will be responsible when something goes wrong? The answer cannot depend solely on existing bank card and corporate account systems. Machine-native transactions require payment infrastructure designed for autonomous software operations.
Key Takeaways
-
Machine-native transactions are transactions in which AI agents autonomously discover opportunities, make decisions, execute payments, and complete settlement.
-
AI Agents need independent accounts, programmable permissions, and stable settlement assets to evolve from chat tools into execution agents.
-
Traditional payment systems were designed primarily for humans and have limitations when supporting cross-border, low-value, high-frequency, and automatically authorized transactions.
-
Crypto payment infrastructure typically includes wallets, stablecoins, smart contracts, identity systems, and reputation systems.
-
Stablecoins are well suited to machine pricing and cross-border settlement, but they remain exposed to reserve, freezing, network, and smart contract risks.
-
The key to AI wallets is not giving models direct control of private keys, but creating revocable execution permissions with clearly defined limits.
-
Scaling the machine economy will also require solutions for identity verification, proof of fulfillment, liability allocation, and dispute resolution.
What Are Machine-Native Transactions?
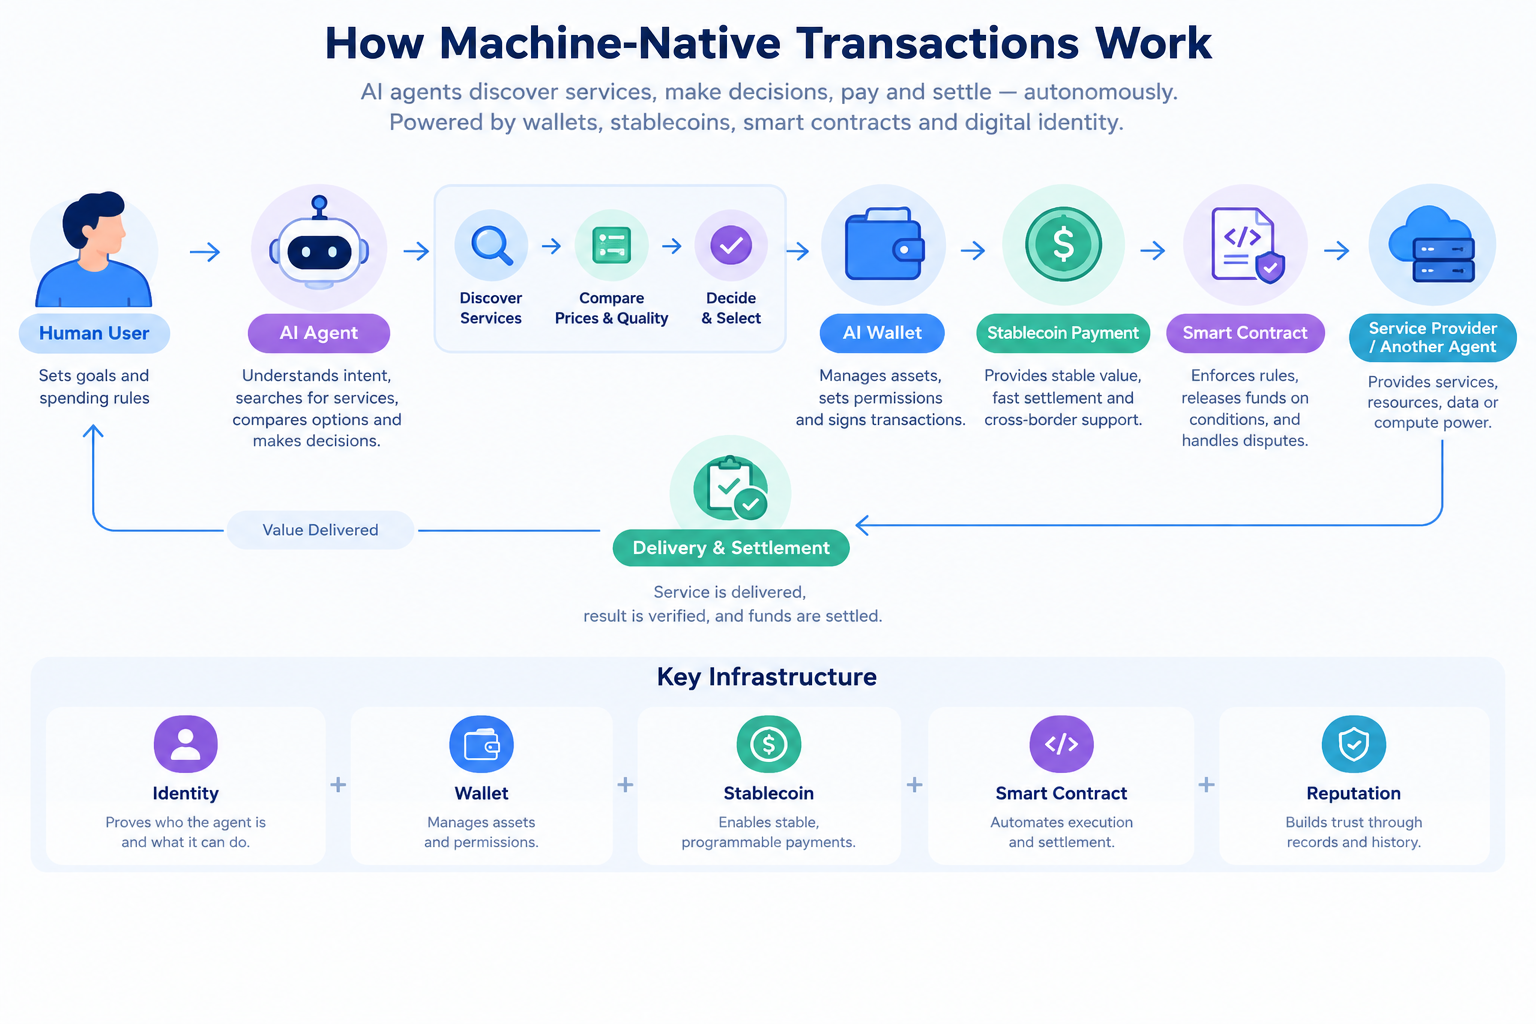
Machine-native transactions are more than the automation of human transactions. They treat software agents as primary participants from the outset of the transaction design. In a traditional transaction, a user typically opens an application, selects a product, logs in, enters payment information, confirms the order, and waits for the merchant to fulfill it. A machine-native transaction, by contrast, may be completed through collaboration among multiple agents:
One procurement Agent interprets the requirements; one search Agent finds suppliers; one evaluation Agent compares pricing, quality, and reputation; one payment Agent executes settlement; and another monitoring Agent tracks the delivery outcome.
The core concept is not having a machine click buttons on a user's behalf. It is giving the machine limited but verifiable economic autonomy. The machine must know who it is, how much it can spend, what it can buy, whom it can pay, and how events can be traced when a dispute arises.
Machine-native transactions can span digital content, cloud computing resources, datasets, model calls, software services, advertising traffic, and logistics resources. Because most of these products can be identified and delivered directly by software, they are especially well suited to automated discovery and purchase by AI Agents.
Why Do AI Agents Need Independent Payment Capabilities?
Most AI chat tools today can answer questions or generate content, but they cannot directly perform financial operations for users. To move from information assistant to execution agent, an AI agent needs at least three payment capabilities.
-
Account capabilities. An Agent needs an account that can receive and send funds, and that account should be tied to specific permissions. For example, a customer service Agent may be permitted to spend $1,000 per month on APIs but should not be able to withdraw the company's entire balance.
-
Authorization capabilities. Users should not hand a model unrestricted control of a private key. If the model is manipulated, compromised, or makes an incorrect decision, the resulting loss could be irreversible. A safer approach is to impose limits on amounts, counterparties, time windows, and asset types so that the Agent can operate only within clearly defined boundaries.
-
Settlement capabilities. An AI Agent may need to make small payments to platforms in different countries, or purchase computing resources every minute. The payment system must support 24/7 operation, low fees, rapid confirmation, and programmatic access.
Without independent payment capabilities, an AI agent remains software that can talk but cannot act economically. A human must log in, approve, and pay at each critical step. This materially reduces automation efficiency and limits coordination among multiple agents.
Why Are Traditional Payment Systems Difficult to Use for Machine Transactions?
Traditional bank cards, bank transfers, and electronic wallets can support certain automated workflows. However, their account structures and risk-control models were built primarily around human users and businesses.
-
Account opening and identity verification are resource-intensive. Bank accounts generally require a real person or company to assume legal responsibility, while a software Agent may be a temporary instance that exists for only minutes or hours. Creating a full bank account for every Agent would be costly and difficult to manage.
-
Traditional payments are often constrained by business hours, settlement cycles, and cross-border restrictions. AI Agents need to access services globally at any time, but payment networks, currencies, compliance requirements, and clearing cycles vary across jurisdictions.
-
Machine transactions may involve tiny amounts at very high frequency. An Agent could purchase dozens of data queries or model inference services every second. If each transaction requires credit card authorization, manual risk review, and traditional clearing, the fees and latency may exceed the transaction's value.
-
Traditional authorization chains lack the necessary flexibility. A user can give a platform access to a bank card, but it is difficult to specify granular rules such as: pay only verified hashrate suppliers, spend no more than $5 per transaction, and keep the daily total below $100. The machine economy requires more granular programmable permissions.
This does not mean banks will be fully displaced. Banks may continue to handle fiat on- and off-ramps, corporate settlement, and regulatory review, while blockchains and stablecoins provide fast payments and cross-platform settlement between machines.
What Components Make Up Crypto Payment Infrastructure?
Crypto payment infrastructure for AI agents generally includes wallets, stablecoins, smart contracts, identity systems, and transaction records.
A wallet is the tool an Agent uses to manage assets and sign transactions. It does not need to be a conventional mobile wallet. It may instead be a programmatic account controlled by a hardware security module, a custodial service, or a smart contract.
Stablecoins are the most common settlement assets for machine payments. Compared with highly volatile crypto assets, dollar-denominated stablecoins are better suited to pricing, budget management, and supplier settlement. An Agent can purchase API calls, data services, or cloud resources based on dollar values, reducing uncertainty caused by exchange-rate fluctuations.
Smart contracts can encode payment conditions directly into software. For example, funds can be released only when a service provider returns a valid result. If the service is interrupted, the remaining balance can be returned automatically. If a transaction exceeds its limit, the contract can reject it outright.
Identity systems answer the question, “Who is this Agent?” Identity does not have to correspond to an individual's real-world identity. It may also take the form of a verifiable credential issued by a platform to show that an Agent belongs to a particular user, company, or service provider.
On-chain records provide traceability. Transaction times, amounts, recipient addresses, and authorization rules can be verified, which supports auditing and dispute resolution. However, on-chain records only prove that a transaction occurred; they do not prove that the AI made the correct procurement decision.
The Role of Stablecoins in Machine-Native Transactions
Stablecoins are valuable not only as crypto versions of the dollar, but also because software can call and compose them directly.
For AI Agents, stablecoins offer three clear advantages.
First, they provide a stable unit of settlement. Hashrate, data, and API services are generally priced in dollars. Stablecoins reduce exposure to price volatility, making budget controls easier for Agents to execute.
Second, they are usable across borders. Payment networks in different countries are not interoperable, whereas stablecoins can move across the same blockchain. Service providers do not need to integrate with a separate bank card network for every country.
Third, they are highly programmable. Smart contracts can release stablecoins based on time, results, or usage, while also applying multisignature, spending-limit, and whitelist rules.
Stablecoins are not risk-free, however. An issuer's reserves, redemption mechanism, freezing authority, and regulatory status can all affect usability. Machine transactions also face risks such as network congestion, smart contract vulnerabilities, incorrect addresses, and issuer-imposed freezes.
Stablecoins are therefore well suited to serve as settlement tools for the machine economy, but they cannot form a complete payment system by themselves. Identity, permission, and dispute-resolution mechanisms are also required.
How Can AI Wallets Enable Agents to Execute Transactions?
An AI wallet is the intermediary between a model and a blockchain account. Its essential function is not to give the model direct access to a private key, but to convert natural-language instructions into constrained transaction requests.
For example, a user might tell an Agent: “Purchase the cheapest GPU hashrate available within the next 24 hours, spend no more than $50, and use only verified suppliers.” The wallet system would need to break that instruction into supplier screening, price comparison, risk checks, limit verification, and final signing.
A comprehensive AI wallet typically contains four modules:
-
Intent parsing: interpreting the task the user wants to complete;
-
Policy engine: translating the task into limits on amounts, assets, addresses, and time;
-
Risk control: checking contracts, recipients, price volatility, and anomalous behavior;
-
Signing and execution: completing the transaction once all conditions are satisfied.
Security designs may include limit-based accounts, temporary keys, transaction whitelists, delayed execution, and multiparty approval. High-risk transactions should require human confirmation rather than being delegated entirely to a model.
Ultimately, an AI wallet's core competitive advantage may not be how smoothly the model responds, but whether it can execute user intent accurately without compromising security.
How Can Machines Establish Identity and Credit?
Machine-native transactions cannot rely on wallet addresses alone. An address can be created, abandoned, or reused, so it provides little assurance about whether the Agent behind it is trustworthy.
A more complete machine identity system should include:
-
The Agent's unique identifier;
-
The user or organization to which it belongs;
-
Its software version and permission scope;
-
Verifiable service records;
-
Its payment and fulfillment history;
-
Its revoked or suspended status.
Machine credit also cannot simply copy the model of personal credit scores. An Agent may have an excellent reputation for data procurement but lack the qualifications required for financial transactions. Credit assessments therefore need to account for the task type, transaction amount, and service domain.
Smart contracts can record fulfillment outcomes, deposits, and dispute-resolution events, but on-chain systems still depend on trusted data sources. For example, confirming that a service provider actually delivered valid data may require an oracle, third-party verification, or a zero-knowledge proof.
The machine economy therefore needs more than payment networks. It also needs infrastructure for machine identity, reputation, and arbitration.
Use Cases for Machine-Native Transactions
Cloud computing and AI inference are among the most straightforward use cases. An Agent can purchase GPU, model-call, and storage resources in real time based on task volume, then automatically release unused capacity when the task ends.
Data marketplaces are another important area. A research Agent can automatically purchase weather data, financial market data, logistics information, or industry reports and pay according to the number of calls.
Software services are similarly well suited to machine payments. Different Agents can settle translation, search, risk-control, identity-verification, and content-moderation services based on API usage.
In digital advertising, an advertising Agent can automatically purchase traffic, verify impression results, and settle with media providers. Smart contracts can release funds based on clicks, conversions, or other verifiable events.
Cross-border trade and supply chains may require more sophisticated machine collaboration. Procurement Agents, logistics Agents, insurance Agents, and settlement Agents can work together to handle quoting, transportation, acceptance, and compensation.
These use cases share several characteristics: the services are identifiable by software, transaction frequency is relatively high, participants may operate across different platforms or countries, and the cost of processing each transaction manually is high.
Current Security and Compliance Risks
The greatest risk of machine-native transactions is that AI autonomy can amplify the impact of an erroneous transaction.
A model may misunderstand user intent, select the wrong supplier, accept a fraudulent quote, or execute a malicious operation after a prompt injection attack. Unlike an ordinary chat error, a payment error is often irreversible.
Private key and permission management are also critical. If an Agent uses a permanent private key and the model or operating environment is compromised, an attacker may be able to transfer assets directly. Temporary permissions, spending limits, and multilayer signatures offer a safer alternative.
Smart contract vulnerabilities can cause systemic losses. Even when the Agent itself makes no incorrect judgment, a reentrancy vulnerability, manipulated price oracle, or misconfigured permission in the contract could result in stolen funds.
Compliance issues are even more complex. Who is the transaction party: the user, the AI developer, the wallet service provider, or the platform operating the Agent? If an Agent pays a sanctioned address, who is liable? Different jurisdictions may reach different conclusions.
Machine transactions may also involve money laundering, sanctions evasion, wash trading, and market manipulation. Open payment networks must balance privacy protection with regulatory visibility.
When Could the Machine Economy Truly Take Off?
Machine-native transactions will not mature simply because a wallet launches or a blockchain supports stablecoins. At least four conditions must be met.
First, AI Agents need sufficiently reliable task-execution capabilities. They must understand constraints rather than merely generate text that appears reasonable.
Second, payment permissions must be controllable. Users need to be able to limit amounts, assets, suppliers, and transaction frequency, as well as revoke authorization at any time.
Third, machine identity and reputation systems must be recognized across platforms. Otherwise, every service provider will need to verify each Agent separately, reducing automation efficiency once again.
Fourth, liability and dispute-resolution rules must be clear. For high-value transactions, irreversible on-chain transfers alone are not enough. Custody, insurance, arbitration, and refund mechanisms are also necessary.
In the short term, machine-native transactions are more likely to begin with digital services and small-value payments than with high-value financial transactions. Cloud resources, APIs, data, and software subscriptions offer clear delivery, easy automated verification, and strong cross-border demand, making them ideal early applications.
Conclusion
Machine-native transactions represent AI's transition from providing answers to executing economic activity.
When AI agents can autonomously purchase hashrate, access data, subscribe to software, and pay other Agents, traditional account systems will appear increasingly inflexible. Stablecoins provide a relatively stable unit for cross-border settlement, blockchains provide open payment rails, and smart contracts can encode spending limits, conditions, and delivery rules directly into software.
Crypto payments, however, are not a complete answer for the machine economy. The industry's ability to scale will depend on the reliability of AI decision-making, the security of wallet permissions, machine identity, service verification, and regulatory accountability. Any solution focused only on AI's ability to transfer funds automatically overlooks the hardest part of machine transactions: balancing automation with control.
The machine economy of the future may not be a financial system without human oversight. Instead, it may be a new collaborative network in which humans set the boundaries, AI handles execution, and blockchains handle settlement and auditing.
FAQ
What Is the Difference Between Machine-Native Transactions and Automated Payments?
Automated payments generally execute fixed rules, such as an automatic monthly debit. Machine-native transactions, by contrast, involve an AI Agent proactively finding services, comparing terms, and completing multistep transactions based on a goal. Their decision-making scope is broader.
Why Do AI Agents Need Crypto Wallets?
Crypto wallets can provide Agents with more flexible programmatic payment capabilities through smart contracts, limit-based accounts, and temporary keys. However, a wallet should never give a model unrestricted access to a private key.
Are Stablecoins the Only Option for Machine Payments?
No. Bank deposits, electronic money, and platform credits can also support machine payments. Stablecoins stand out for their cross-border usability, 24/7 availability, programmability, and compatibility with smart contracts.
Can AI Agents Spend Money Completely Autonomously?
Limited autonomous payment is technically possible, but granting unlimited permissions is not recommended. A safer approach is to establish spending limits, whitelists, time windows, risk levels, and human approval requirements.
How Can Machines Prove That They Are Trustworthy?
Trust can be assessed using verifiable identity, service records, deposits, historical fulfillment data, third-party certification, and on-chain reputation. Machine credit is generally context-specific, however, and cannot be reduced to a single score for every type of transaction.
Will Machine-Native Transactions Replace Bank Cards?
Not in the short term. Bank cards and bank accounts remain well suited to personal spending, payroll, fiat settlement, and compliant financial services. Machine payment infrastructure is more likely to supplement existing systems first by supporting digital transactions involving APIs, data, and hashrate.
What Is the Biggest Risk of Machine-Native Transactions?
The primary risks include AI misjudgment, prompt injection attacks, private key exposure, smart contract vulnerabilities, fraudulent services, unclear regulatory liability, and irreversible transfers. As automation increases, so do the requirements for permission controls and auditing.
Related Articles
Will Sidra Break $1,000? A Realistic Look at Sidra Chain Price Claims in 2026–2027
BlockDAG (BDAG): A High-Speed and Secure Layer 1 for the Next Era
Rising Prices but Bearish Funding Rates: Is Crypto Entering a “Layered Bull Market” After Wall Street Capital Inflows?
Fractional NFTs: Lowering Barriers and Enhancing Liquidity
What is USDC? A Complete Guide to One of the Most Trusted Stablecoins